Loading…
Financial Clarity and Advanced Wealth Planning
The Acanto Experience
A clear path from clarity to confidence. Understanding where you stand starts complimentary.
1
Discover
Complimentary
Your personalized Asset-Map®. No obligation, no cost. We identify potential gaps and risks.
2
Plan
One-time planning fee
Financial forecasting and stress testing, tax, insurance, and estate coordination, plus your online vault.
3
Implement
Investment management
Together, we implement adaptive strategies that seek to help grow your wealth and manage risk.
4
Maintain
Ongoing Clarity
We monitor your investments and adapt those strategies as your life and the markets change over time.
Go Beyond Simply Investing:
The “6 Ls” of Financial Security
The Asset-Map® provides clarity. The “6 Ls” provide a template to design for. Independence gives us access to a range of financial products to help secure your 6 Ls. Intelligence drives our strategy design, to help you pursue your goals. Integrity, as your fiduciary, requires full disclosure of costs, risks, pros, cons, and conflicts of interest.
Liquidity
Do you have enough accessible cash for emergencies and opportunities?
Long-Term Disability
Would your income continue if you could not work?
Life Insurance
Is your family's future secure if something happens to you?
Long-Term Care
Do you have a plan for potential healthcare costs in retirement?
Longevity
Will your assets last as long as you do? Are you prepared for a long life?
Legacy
Are your estate documents in order to pass wealth efficiently?
Acanto's Client experience: A Detailed Runthrough.
Open any step for the full details, and close it again to return to the short list.
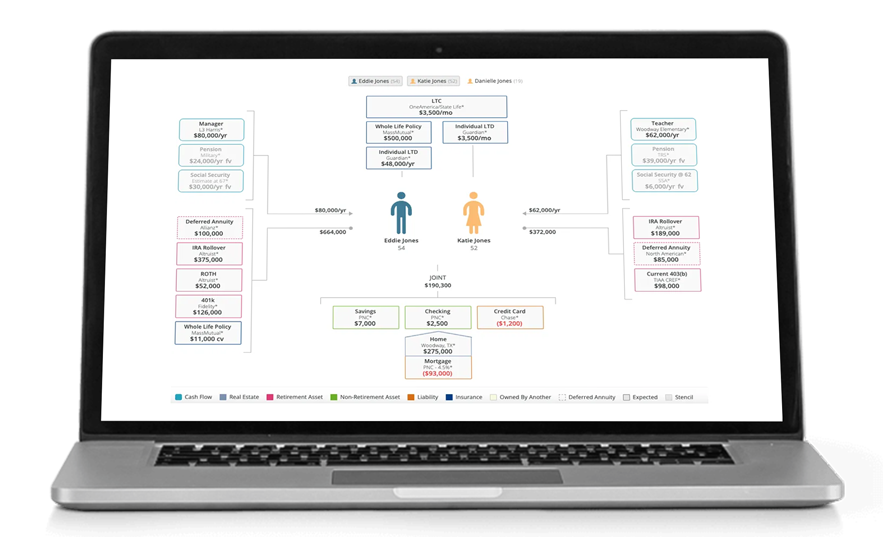
We don’t just “organize” your finances into a single, complete view. Together, we build your family’s Asset-Map® as a crucial starting point to identify blind spots and gaps across your current financial situation. This confidential and complimentary diagnostic exercise provides the clarity needed to design strategies intended to help protect your family and achieve your financial goals.
The Asset-Map® typically takes about 15-30 minutes to complete securely online and is followed by an approximately one-hour video review session to discuss findings and potential next steps, when appropriate.
New to the idea of planning as one connected system? Read What Is Holistic Financial Planning?
- See Where You Are: A clear, single-page view of your entire financial reality.
- Find the Gaps: Instantly spot missing protections, tax inefficiencies, and diversification gaps.
- Build the Structure: The foundation for a plan that goes beyond standard 60/40 allocation.
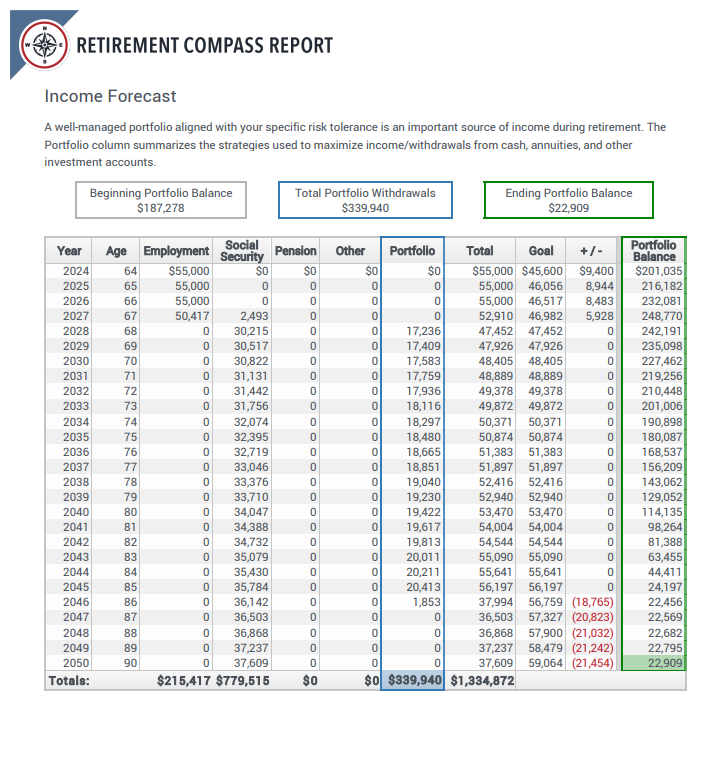
For all new clients, we deliver a comprehensive retirement analysis package developed in conjunction with trusted CFP® professionals. We dig deeper into your current financial situation, designed to bring clarity to your entire financial world. From there, we produce a full retirement analysis to understand how vulnerable your current financial life may be to major events—from the loss of a family member to a severe market downturn. We provide a set of personalized, easy-to-read reports, stored in a secure online "Digital Vault" alongside any other critical documents you wish to upload, such as Wills, Trusts, and Estate documents. Utilizing your existing financial, tax, and PIA (Social Security benefit), we create a package that includes:
- Financial Overview
- Roth Conversion “Found Money” Analysis (how the Roth IRA five-year rule works)
- Color of Money Risk and Tax Analysis
- Secure Digital Vault for Key Documents
- Social Security Maximization Report
- Portfolio Review
- Asset Allocation Roadmap
We utilize a combination of strategies, including:
- Systematic ETFs
- Acanto's Dynamic Allocation Models
- Buffered ETFs and Structured Notes
- Comprehensive Retirement Report
- Sequence of Returns Risk Analysis
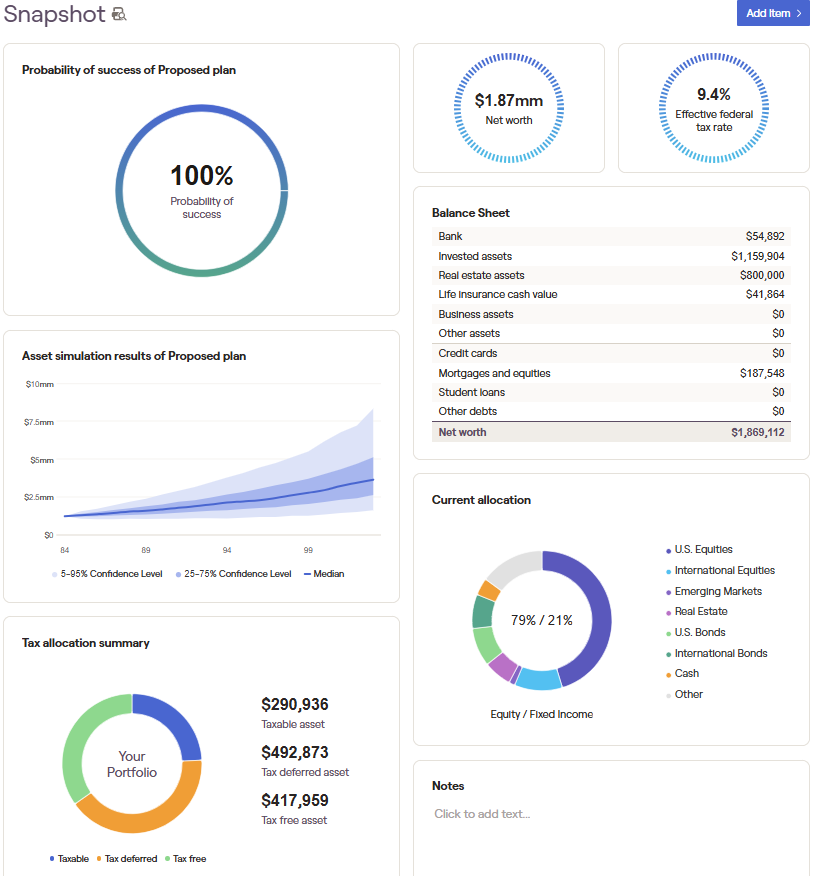
For those who want ongoing Financial Clarity, we build a living, breathing financial plan using planning software such as RightCapital™ and other platforms. Whether you need to model a stock vesting plan, RMDs, insurance cash values, real estate income, legacy optimization, or simply want to stress-test your financial future, this portal adapts as your life evolves. You can create detailed expenses, adjust return assumptions, explore how your decisions fit together, and securely store critical documents, all in one place.
- Quarterly Reviews & Monitoring
- Estate Planning (how estate coordination works with your attorney)
- Insurance and Annuity Modeling
- Real Estate Income
- Tax Optimization
- Stock Option Vesting Projections
- Budgeting and Spending Analysis
- Lifetime Cash Flows Analysis
- Secure Online Vault for Critical Documents
- 24/7 Client Access to Model Changes and Edit Assumptions
- Linked Accounts Update Automatically
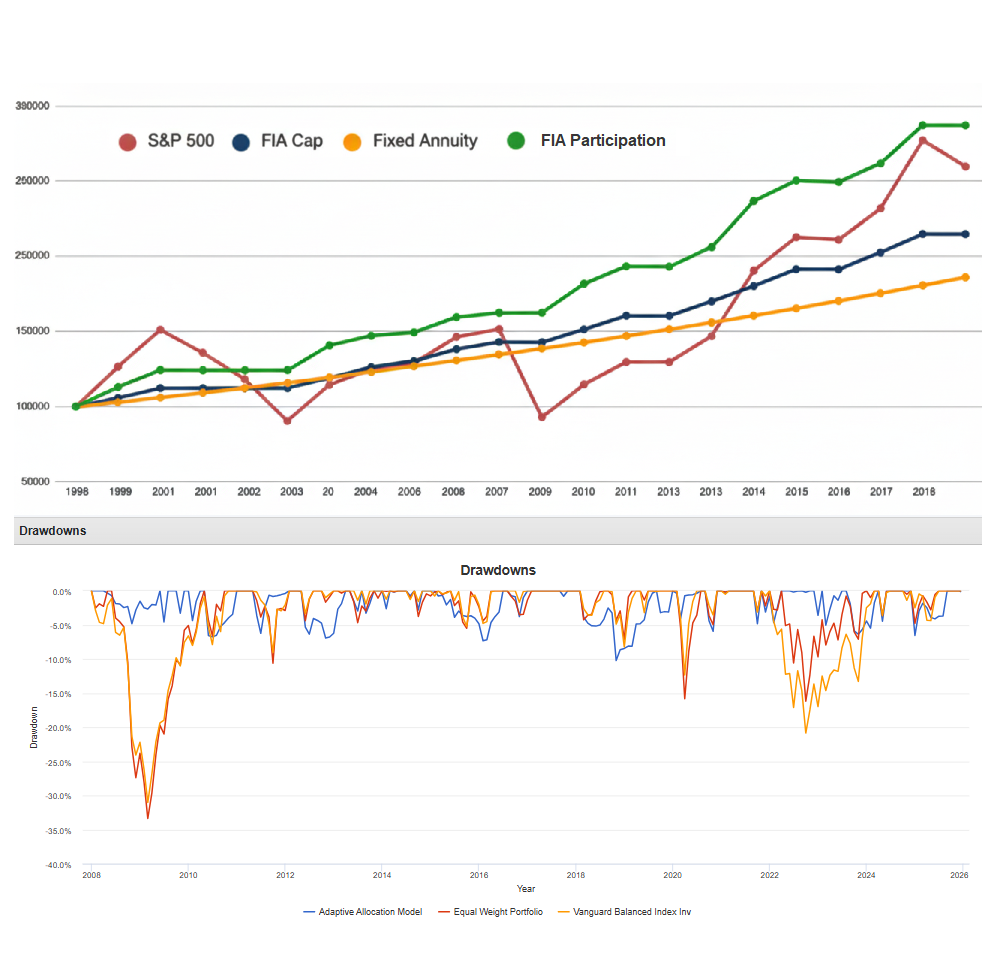
In a world of AI and rapid economic change, "buy and hold" isn't enough. We use modern tools that seek to manage downside risk* and help reduce the emotional and financial strain of market declines.
We utilize a combination of strategies, including:
- Tactical Asset Allocation
- Whole Life and Term insurance
- Buffered ETFs and Structured Notes
- Fixed Index Annuities
- Health and Income Riders
- Alternative Investments (Interval Funds, Hedged ETFs)
- MYGAs and SPIAs for short-term asset relocations
- Trusts and Asset Protection
Tactical allocation has limits, including costs, taxes, and adjustments that may not help. To see how it compares with a fixed long-term mix, read tactical vs strategic asset allocation.
*Investing involves risk, including the potential loss of principal. No strategy can guarantee a profit or protect against loss in periods of declining values.
How We Are Compensated
Clear, and agreed in writing before you decide. Your Asset-Map® is complimentary.
Your planning fee covers the work of building your plan. It is separate from any investment management fee and is not credited against it.
| Complimentary review of your situation. The more detail you share, the better. | Complimentary |
| Service | Fee | Type |
|---|---|---|
| Comprehensive plan, simple situation | $1,500 to $3,000 | Fixed fee |
| Comprehensive plan, standard household | $3,000 to $5,000 | Fixed fee |
| Comprehensive plan, complex family or estate planning | $5,000 to $10,000 | Fixed fee |
| Annual plan review (planning-only clients) | $500 to $1,500 | Fixed fee |
| New projects and extra meetings | $300 | Per hour |
The fee depends on the complexity of your situation and is agreed in writing before work begins. $1,000 is due when you sign, and the balance is due when your plan is delivered. We target delivery within 15 business days, and no later than 30 days after your information is complete. Households with over $5 million in assets are quoted individually. The planning fee is separate from any investment management fee and is not credited against it. Your planning engagement includes an online document vault and access to your planning materials and projections.*
Planning clients receive an annual plan review. Investment management clients are offered quarterly reviews as standard, with the annual plan review included. After three years as a client, your annual fee (review or management) is reduced by 10%. This applies to every client, regardless of assets or services used.
*Standard platforms, such as the document vault and certain other planning software, are included in your fee. Optional add-ons, such as real-time data feeds and additional features, may carry additional fees. Any add-on is quoted before you decide and is never added automatically.
| Managed assets (annual rate) | Core portfolios | Adaptive strategies |
|---|---|---|
| First $1,000,000 | 1.25% | 1.50% |
| $1,000,000 to $3,000,000 | 1.00% | 1.25% |
| $3,000,000 to $10,000,000 | 0.80% | 1.05% |
| Over $10,000,000 | 0.65% | 0.90% |
Each rate applies to the dollars in that band. Core portfolios are index-based. Adaptive strategies include our active strategies and models and passive-plus portfolios, such as alternative ETF models, and add 0.25% to the base rate. The add-on reflects the additional work involved and the account type. Because Acanto earns a higher fee on adaptive strategies, this is a conflict of interest, which we disclose in Form ADV Part 2A. We do not require a minimum account size, but some strategies require a minimum to implement properly.
Rates shown are annual rates. Management fees are billed quarterly in arrears. Custodian, brokerage, and fund or ETF expenses are separate.
Fees may be negotiable in certain circumstances, at Acanto's discretion, and different clients may pay different fees for similar services. See Form ADV Part 2A for details.
Projections are estimates and are not guarantees. Investing involves risk, including the potential loss of principal. Details on services, fees, and conflicts of interest are in our Form ADV Part 2.
Start with Clarity. Your Initial Asset-Map® Is Complimentary.
www.acantollc.com/services | (914) 714-0735 | Support@acantollc.com
3 Planning Examples: Clarity in Action
Three real planning conversations, with identifying details left out. Open any one to see the situation, the approach I discussed, and what it illustrates.
The Situation
A 79-year-old widow worried she might outlive her savings. Most of her wealth sat in her large home, and her projected expenses showed her IRA accounts could run out in about 7 years, leaving a state pension and no Social Security. Meanwhile, her daughter was looking for a home where the two of them could live together.
The Approach I Discussed
I walked through an unconventional idea: a sale-leaseback. Her daughter would buy the home with a loan of roughly 4% or more, and the proceeds could go toward income solutions such as annuities with healthcare, liquidity and inflation-protection features. The house would then sit on the daughter's Asset-Map®, which may change how it is treated for long-term care and Medicaid purposes. Ideas like this come with real trade-offs: annuity guarantees depend on the issuing insurer, and funds may be less accessible. A qualified estate attorney and tax professional would need to review it.
What This Illustrates
It shows what can happen when income, home equity, family needs and long-term care are looked at together instead of one at a time. The family is reviewing the plan in stages. Every household is different, and no result is implied.
#Sale-Leaseback#Long-Term Care Planning#Income Planning
The Situation
During what was meant to be a standard planning review, something important surfaced: a stepson who had gone blind five years earlier. The existing plan had nothing in place for his long-term care, and it had not accounted for the family's tax situation or how his eligibility for government benefits could be affected.
The Approach I Discussed
I discussed a special needs trust, which may help protect eligibility for government benefits, alongside a Roth conversion, which may change the family's tax picture but means paying tax sooner. Both involve trade-offs, and both need review with a qualified estate attorney and tax professional.
What This Illustrates
One conversation about a family member changed the questions we asked about taxes, benefits and estate documents. A good planning review starts with the whole family, not only the accounts. Results vary, and no result is implied.
#Special Needs Trust#Roth Conversion#Tax-Aware Planning
The Situation
A client with an aggressive investment profile unexpectedly lost their job. Their question: how do we shift from building wealth toward preserving it, keep long-term growth in view, and still have cash available, while markets are volatile and income has stopped?
The Approach I Discussed
Rather than a static buy-and-hold approach, I discussed our adaptive investment toolkit, which seeks to manage risk while planning for the liquidity needed during the gap in income. Adaptive strategies can underperform, and trading can create costs and taxes.
What This Illustrates
Life changes, and a plan sometimes has to change with it. Investing involves risk, including the potential loss of principal, and no strategy can guarantee a result or protect against loss.
#Adaptive Strategy#Liquidity Planning#Career Transition
*These examples are based on client situations with identifying details omitted. They are not testimonials or endorsements, do not represent every client's experience, and do not guarantee or imply any future result. Strategies may not suit every investor. Planning decisions require review with qualified legal and tax professionals.
See How Our Investment Approach Fits the Plan
Explore our investment strategies and the research behind the approaches we discuss as part of a broader planning conversation.
Explore Our StrategiesReady to gain clarity?
Start Your Asset-Map®Prefer to talk first? Schedule a complimentary 30-minute introductory call